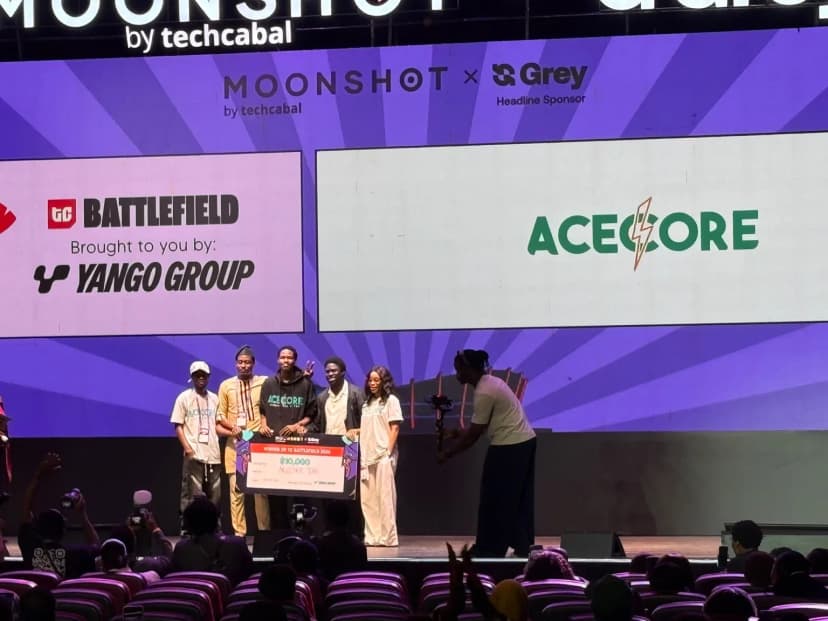
Fintech executives told the Moonshot by TechCabal 2026 event that taking digital payments is only a starting point in a business's adoption of technology. They said providers must also help firms handle cash flow, get to know their customers and cut down on fraud.
On a panel called "The Business Behind the Transaction", speakers from Mastercard, Remita and OPay argued that merchants want services that link payments to the rest of their operations. They also want dependable support and training for their staff.
Read More: CBN Deploys Fintech Giants In New Anti-Money Laundering Pilot
“Let’s understand the customer, let’s solve for the customer problem rather than providing a generic product push across the different businesses,” said Shabir Ahmed, Mastercard’s Senior Vice President for Customer Solutions in Central Africa.
Connectivity and Digital Payments
Ahmed named connectivity, intelligence drawn from data, and trust as the areas providers should focus on if they want to help businesses run better. His remarks showed that payment technology is only as valuable as what a business can do with it once the money has been collected.
Abimbola Onyluka, who leads the division at Remita covering both corporate clients and consumers, explained how the company intends to widen its range of services:
- Offering to cover managing finances,
- Issuing invoices and
- Meeting statutory compliance obligations.
She said businesses require tools that link their financial records with lenders, regulators and banks. A digital payment record gains value when it can back up a loan application, support reporting and inform choices about running the business.
Yet a broader product range also obliges providers to keep the payments operations at their core dependable. Onyluka underlined the importance of reliable support and swift fixes when systems go down, since failed digital payments can halt sales and hurt customer service.
Businesss Digitization
Isimeme Ayobami Owobo, who directs key account merchants at OPay, said the companies that grew fastest were those that built technology into their daily operations and taught their staff to use it well.
He argued that simply putting in a payment terminal covered only a small share of the work. Merchants, he said, should also get more from the other tools they have. One example is the digital payment model, QR code, which can make transactions quicker.
Read More: Essential Documents Used in Foreign Trade Transactions Worldwide
The conversation pointed to a difficulty facing payment firms that want to play a bigger part in the businesses they serve. Handling a transaction puts them in touch with the buyer. Extending that link into a wider service, though, demands knowledge of how each individual business runs.
Put simply, the executives held that taking digital payments is a narrow yardstick for judging how far a business has gone digital. The real gain arrives when firms put the data produced by their transactions to work in handling cash, serving customers and planning for growth.
This story was first reported by TechCabal.